Articles
ABA Article - Institutional Friction Impedes Innovation
Context In its previous Article 1, Abelian argued that strategy is only valuable when it creates meaningful change...
September 14, 2026

April 13, 2021
With forward-looking SOFR term rates not expected to be available anytime soon, market participants will have to rely on a calculated term rate. In addition to the increasing operational complexity that comes with a calculated term rate, participants have to decide which version of a calculated SOFR term rate to use.
In June 2017, the Alternative Reference Rate Committee (ARRC) announced the choice of Secured Overnight Funding Rate (SOFR) as its recommended alternative to LIBOR. SOFR is a transacted rate referencing a deeply traded repo market. The immediate concern around this choice was that LIBOR was a term rate (with 1M and 3M terms being the most commonly used) while SOFR was an overnight rate. To address these concerns, the ARRC's "Second Report" in 2018 provided the following guidance:
"...the ARRC has explicitly included a goal of producing a forward-looking term rate for use in cash products in its Paced Transition Plan... The ARRC believes that this final step could be accomplished by the end of 2021."
The ARRC also stated that a forward-looking term rate's publication depended on having sufficient depth in the SOFR Derivatives market. Despite this caveat, most market participants expected that a forward-looking SOFR term rate would eventually emerge.
However, in March 2021, the ARRC provided the following update:
"The Alternative Reference Rates Committee (ARRC) will not be in a position to recommend a forward-looking Secured Overnight Financing Rate (SOFR) term rate by mid-2021, and it encourages market participants to continue to transition from LIBOR using the tools available now"
This announcement was not a complete surprise to participants who had been watching the volume of SOFR derivatives (especially the short end of the curve) increase too slowly to provide assurances of a robust implied forward rate. Nonetheless, the announcement took several players aback, putting the onus back on market participants to calculate a term rate.
There are many decisions to be made before arriving at a calculated SOFR term rate. The major decisions are:
In addition to the calculations, the ARRC has recommended different variants of the SOFR Term rate for different products, as depicted in the figure below.
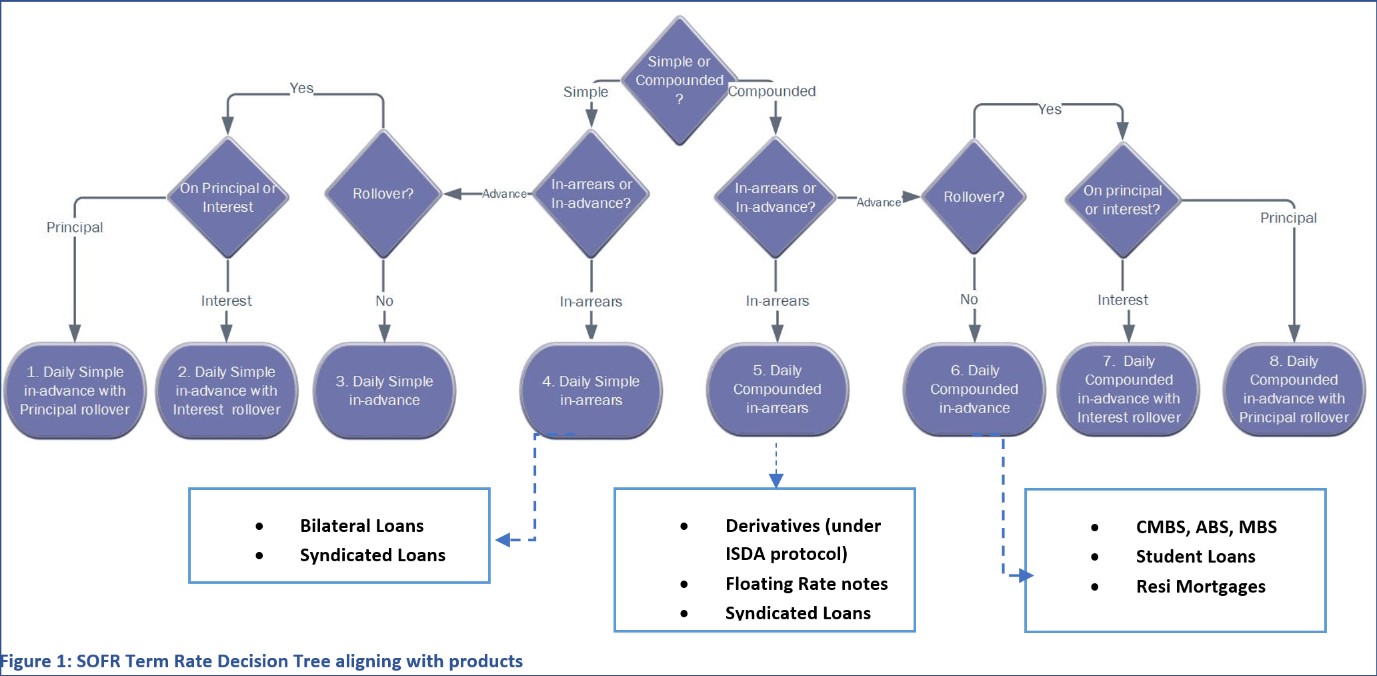
So, where does this leave participants? Abelian Partners has had several conversations with practitioners in US Banks. Broadly, these banks have fallen along the following lines:
The lack of a forward-looking SOFR term rate has complicated efforts to transition away from LIBOR to SOFR. In the absence of a robust alternative to SOFR developing before the year-end, banks will have to manage the complexities of SOFR and act in a coordinated manner to ensure a successful transition. There is not much time left!
Context In its previous Article 1, Abelian argued that strategy is only valuable when it creates meaningful change...
Regional commercial banks are a vital component to funding business and innovation in the United States, but major...
Setting Strategy Every year regional bank management teams step offsite for the standard strategy workshop. Reviews...
Market updates, articles and firm news, sent straight from Abelian. Change preferences or unsubscribe from any message.