Home/Insights/Market Updates/Weekly Market Update - 10/21/2026
Market Updates

Weekly Market Update - 10/21/2026

October 21, 2026

Share
Weekly Market Update - 10/21/2026
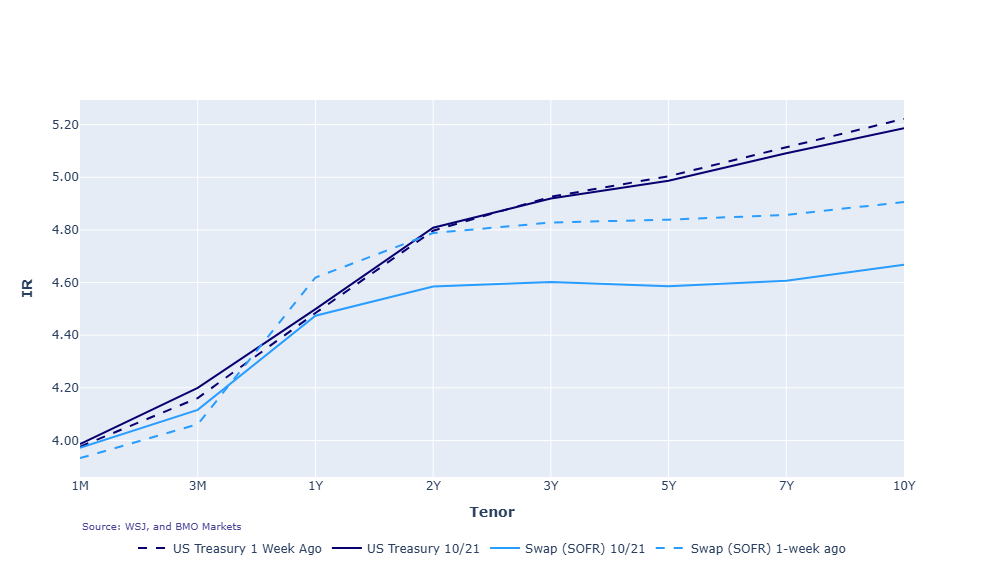
  • Rates: Rates fell this week, with larger declines at longer maturities. Treasury yields were little changed at the front end but fell at longer maturities. SOFR swaps showed a much larger move at longer maturities, with 1-month and 3-month rates unchanged while rates from 1 year to 10 years fell. For banks, this means near-term funding costs are holding steady, while the drop in intermediate and long-term rates shows signs of easing pressure on securities valuations and fixed-rate loan pricing and lowers the cost of hedging longer-duration interest-rate risk.
  • Gas Prices Inflate Retail Sales, Housing Weakens: Retail sales rose 0.8% in September to $745B, beating forecasts, but gas station receipts jumped 6.4%. The labor market held relatively steady: initial jobless claims edged up just 1,000 to 199,000 in the week ended October 10, below 200,000 for a fifth straight week. Housing is moving the other way, as pending home sales fell 7.3% in September and are down 11.3% from a year earlier. Strong headline spending is largely an energy-price story, and the weakness in housing shows how higher borrowing costs are weighing on rate-sensitive parts of the economy.
  • AI Sell-Off Shaves Over $1T from Top AI Stocks: The Nasdaq fell 1.88% and the S&P 500 fell 1.11% on Wednesday, and 20 of the most valuable global AI and semiconductor stocks lost more than $1T in value in the first part of the week. The trigger was concern in the market that higher rates will make it costlier for heavily indebted AI companies to fund their buildouts. The market’s concern has moved from whether AI demand is real to who can afford to finance it at today’s rates.
  • Capital One Beats on Improving Credit and Discover Gains: Capital One’s third-quarter revenue rose 6.4% to $16.34B, and adjusted EPS of $6.69 beat the $5.50 estimate. The domestic card charge-off rate fell to 3.98%, down 65 bps from a year earlier. Provisions for credit losses were $2.9B, well below the roughly $3.6B analysts expected, and an allowance release of about $225mm added to earnings. The company has captured about $1.8B in annualized synergies from the Discover deal. Shares rose about 3.9% in after-hours trading. Consumer credit is holding up even with inflation running hot, though part of the beat came from lower reserves rather than operations.
Share
← Older Market UpdatesNewer Market Updates →

More Market Updates

Market Updates

Weekly Market Update - 11/5/2026

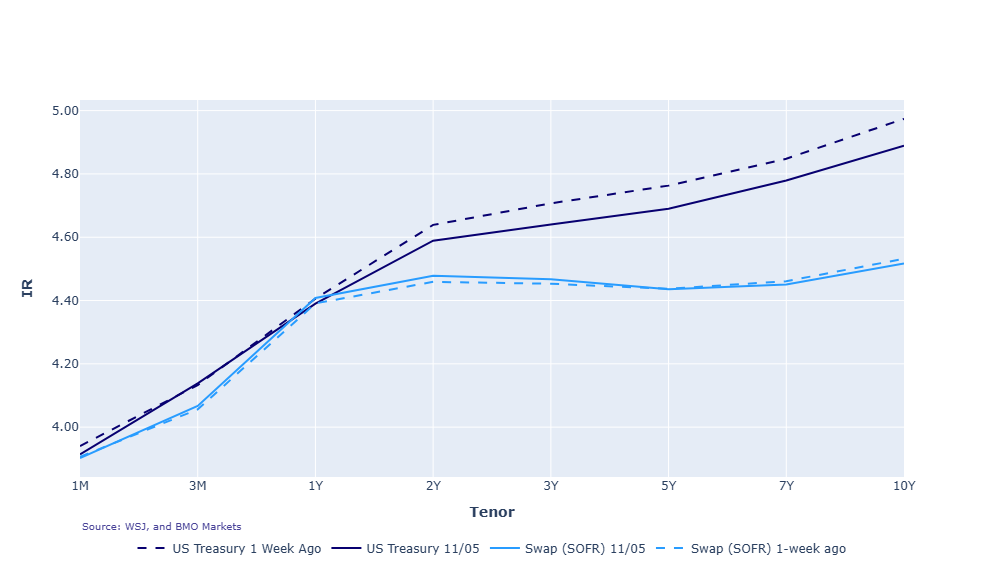
Rates: Rates fell again this week, with the biggest declines in the middle and long end of the curve. Treasury yields...

November 5, 2026

Market Updates

Weekly Market Update - 10/28/2026

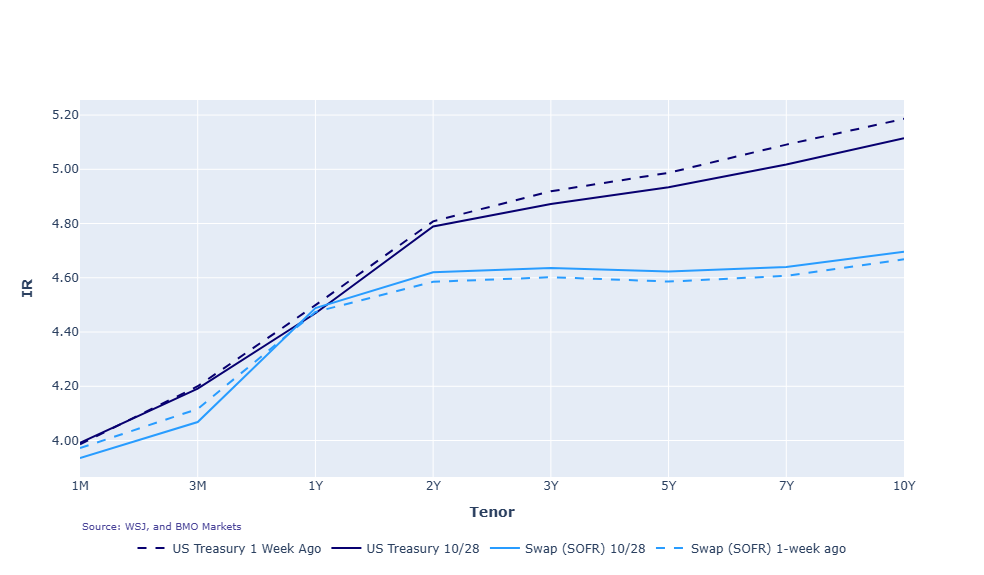
Rates: Rates fell this week, with the biggest declines at longer maturities. Treasury yields were little changed at...

October 28, 2026
Market Updates

Weekly Market Update - 10/15/2026

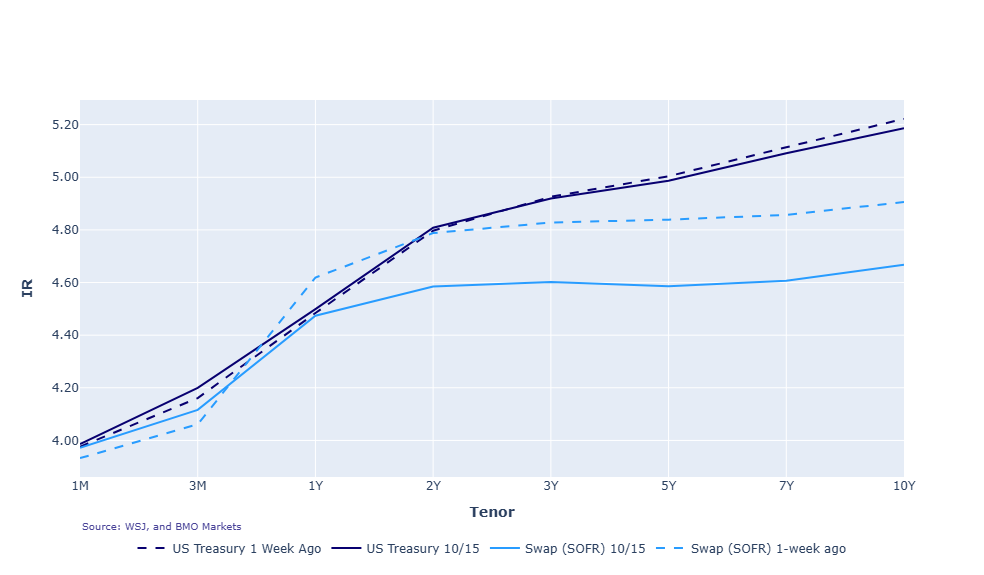
Rates: Yield curves flattened this week. Treasury yields rose slightly 1 month to 1 year but fell at longer...

October 15, 2026
Abelian Insights

Get Abelian’s Perspective

Market updates, articles and firm news, sent straight from Abelian. Change preferences or unsubscribe from any message.
Send Me

Details stay with Abelian and are used only to send the updates selected.